Do Better Energy Grades Actually Increase Property Value?
A commercial building receives an A energy grade, while a comparable property down the street receives a D. Does the first building command higher rent? Can its owner sell it for more? And does improving a building's energy grade actually increase its market value?
Research suggests that energy-efficient buildings can receive higher sale prices and, in some markets, higher rents. However, the relationship is not automatic. Location, lease structure, tenant demand, operating costs, building condition, and regulatory exposure also influence what a buyer or tenant will pay.
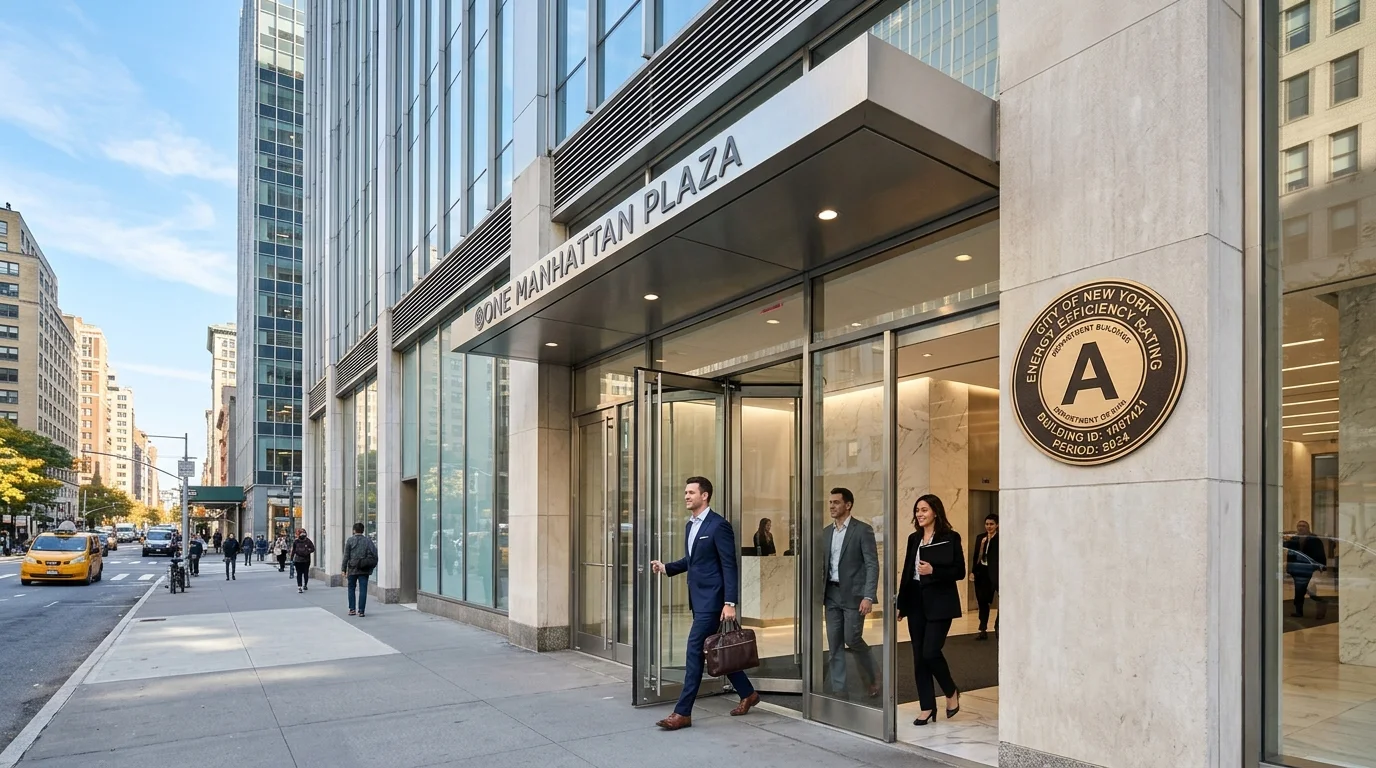
For New York City property owners, this question has become particularly relevant because covered buildings must publicly display energy-efficiency grades under Local Law 33, as amended by Local Law 95. The label creates a visible performance signal that prospective tenants, buyers, brokers, and investors can consider alongside other property information.
The most defensible conclusion from the research is that energy performance can influence real estate value, but a better grade does not guarantee a specific increase in rent or sale price. Understanding the difference between an observed price premium, a genuine causal effect, and the NYC grading system itself is essential before using energy grades in a property investment decision.
What Does an NYC Building Energy Grade Actually Measure?
NYC's energy grades are based on an ENERGY STAR score generated through the U.S. Environmental Protection Agency's Portfolio Manager benchmarking platform. For eligible property types, the score compares a building's measured energy performance with that of similar buildings, accounting for relevant operating characteristics and climate.
Under NYC's current grading framework, the letter grades are assigned as follows:
| NYC energy grade | ENERGY STAR score |
|---|---|
| A | 85 or higher |
| B | 70–84 |
| C | 55–69 |
| D | Below 55 |
| F | Required benchmarking information was not submitted |
| N | Exempt from benchmarking or not covered by the ENERGY STAR scoring program |
Source: NYC Department of Buildings — Local Law 33 Energy Grading.
One distinction matters when interpreting property value: an NYC energy grade is not a direct measure of a building's market value, total carbon emissions, or physical condition.
A building can have an A grade while still requiring substantial capital repairs. Another building may receive a lower grade because of its operating patterns, energy-intensive uses, or inefficient systems, even if its location and tenant demand make it commercially attractive.
An F grade requires particular care. It indicates missing required benchmarking information, not necessarily exceptionally poor measured energy performance.
Consequently, investors should examine the underlying energy data and the reason for the grade rather than treating the letter as a complete assessment of the property.
What the Research Shows: Four Important Findings
Studies have examined energy performance labels, voluntary certifications, regulatory standards, and real estate transactions. Their results are informative, but they measure different things. An ENERGY STAR-certified office, a European residential energy label, and an NYC LL33 grade are not equivalent measures.
 Real estate financial analysts examining property valuation, cap rates, and comparative rent premiums associated with building energy benchmarks.
Study 1: ENERGY STAR Certification and U.S. Office Rents
A study by Becka Brolinson, Karen Palmer, and Margaret Walls examined more than 4,100 U.S. office buildings in research published in the Journal of the Association of Environmental and Resource Economists.
The study found that office-building rents increased by approximately 3.6% following ENERGY STAR certification, while utility expenditures did not show a corresponding change. The researchers also found no evidence that certification itself prompted capital upgrades, suggesting that the label partly served as a signal of buildings that were already energy-efficient.
Source: Resources for the Future — Does Energy Star Certification Reduce Energy Use in Commercial Buildings?
What does this mean for property owners?
The result suggests that a recognized energy-performance signal may contribute to rental value even when certification does not itself produce immediate additional energy savings. Tenants may value the information about a building's performance, and the label may help an owner communicate operational quality.
However, ENERGY STAR certification is not the same as an NYC A or B grade. The 3.6% result should not be used as a guaranteed rent premium for improving a NYC building's letter grade.
Study 2: Energy Labels and Commercial Property Prices in the Netherlands
A March 2026 study published in Nature Communications examined a Dutch policy requiring qualifying office buildings to achieve an energy-performance label of C or better.
The researchers found that offices meeting the label-C requirement experienced a 21.8% increase in transaction prices following the policy's formal adoption, while rental rates remained largely unchanged. The policy announcement was also associated with increased energy-performance improvements among office buildings.
This study is especially relevant because it examines a policy intervention rather than simply comparing high-rated and low-rated buildings.
The result suggests that investors may incorporate regulatory expectations and the risk of holding inefficient assets into purchase prices before comparable changes become visible in rents.
Nevertheless, the 21.8% figure is specific to the Dutch office market and the policy studied. It does not establish that moving a NYC building from a C to an A grade will increase its selling price by the same percentage.
Study 3: Inefficient Office Buildings and Rental Discounts
An earlier study by Nils Kok and Maarten Jennen examined approximately 1,100 commercial office leasing transactions in the Netherlands between 2005 and 2010.
The researchers found that offices with inefficient energy labels of D or worse had rents approximately 6.5% lower than otherwise similar buildings rated A, B, or C.
Source: Energy Policy — The Impact of Energy Labels and Accessibility on Office Rents.
The distinction is important: the study identified an association between poorer energy performance and lower rents after controlling for relevant property characteristics. It does not mean every lower-rated building must offer a rent discount.
In practice, differences in energy costs, occupant comfort, building quality, and tenant preferences can affect whether an inefficient property must compete on price.
Study 4: The Broader Evidence on Energy Efficiency and Asset Values
The International Energy Agency's June 2025 review of energy efficiency and asset values summarized studies across multiple residential and commercial markets.
Its review reported estimated sale-price premiums of approximately 3%–15% for residential buildings and 13%–20% for commercial buildings, depending on the market and study examined.
Source: International Energy Agency — Asset Values.
These ranges are useful for understanding the wider real estate market, but they combine research using different labels, property types, countries, and methods. They are not a single universal premium that applies to every efficient building.
Taken together, the studies suggest that energy performance can affect property value. They also show why a responsible valuation should not rely on one research percentage without considering the property and market being evaluated.
Why a Better Energy Grade Can Influence Rent
A tenant evaluating two office spaces may consider more than the advertised rent. Electricity and heating costs, temperature consistency, ventilation performance, operating reliability, and the quality of building management can all affect the total cost of occupying the space.
A building with strong energy performance may offer lower energy expenses under comparable conditions. It may also have more modern systems and better operating controls, although the energy grade alone cannot confirm that these improvements exist.
The financial benefit to tenants depends heavily on the lease.
Under a lease where the tenant pays utilities directly, reduced energy consumption may lower the tenant's total occupancy cost. Under a lease where the landlord pays utilities, the immediate financial benefit may accrue primarily to the owner.
This creates a potential split incentive: the party funding an energy retrofit is not always the party that receives the direct savings.
A stronger energy grade can therefore affect rental negotiations through several channels:
- Operating expenses: Prospective tenants may favor a property with credible evidence of lower energy consumption.
- Marketability: A documented performance advantage can help a building stand out when competing spaces are otherwise similar.
- Occupant experience: Related improvements to HVAC controls, temperature stability, and ventilation may make the space more attractive.
- Lease negotiations: Tenants may consider total occupancy cost rather than rent alone.
These mechanisms help explain the research findings, but not all benefits are captured by the energy grade itself. A building owner should document actual utility consumption, operating performance, and relevant tenant benefits before making financial claims.
Why Energy Grades May Have a Greater Impact on Sale Prices Than Rents
Property buyers look at the future income and costs associated with owning an asset. A building's energy performance can influence both its expected operating expenses and the capital investments a future owner may need to make.
For example, a prospective buyer may discover that an older office building has a weak energy grade, deteriorating HVAC equipment, and substantial upcoming retrofit requirements. The buyer may reduce the offer price to account for the expected expenditure, uncertainty, and time needed to complete the work.
Another buyer may value a more efficient property because it appears better positioned to manage operating costs and future regulatory requirements.
Rents can respond differently. Tenants may prioritize location, transit access, floor plates, amenities, lease terms, and the immediate cost of occupying a space over the building's energy grade alone.
This difference is consistent with the 2026 Dutch policy study, where sale prices reacted more strongly than rents. It also explains why an owner can improve a building's attractiveness to investors without necessarily being able to increase rents immediately.
Does an NYC A Grade Guarantee Higher Property Value?
No. The NYC grading system is a useful disclosure mechanism, but it does not establish a specific market value.
Property value is influenced by multiple factors, including:
| Property factor | Potential influence on value |
|---|---|
| Location and accessibility | Tenant demand, rental rates, and buyer interest |
| Lease structure and tenant quality | Predictability of income and operating costs |
| Building condition | Maintenance requirements, capital expenditure, and reliability |
| Energy performance | Utility expenses and potential exposure to inefficient operation |
| Regulatory position | Expected costs and risks associated with applicable building requirements |
| Market conditions | Interest rates, financing availability, vacancy, and investor expectations |
An A-grade building in a weak rental market does not automatically outperform a well-located building with a C grade. Similarly, a low-rated property may still command a strong price if its location and income potential are attractive.
A valuation should treat the energy grade as one relevant piece of evidence, not a substitute for an appraisal, rental-market analysis, or technical due diligence.
 Building engineers and valuation specialists verifying equipment upgrades and operating controls to establish real business value beyond the letter grade.
The Special Case of an NYC D or F Grade
A D grade may prompt questions about operating efficiency, potential retrofit requirements, and how the property compares with similar buildings. The owner's next step should be to investigate the underlying energy score and consumption data before choosing an improvement strategy.
An F grade is different. Because it denotes missing required benchmarking information, it may raise concerns about reporting and transparency rather than directly demonstrating poor energy performance.
For a covered building, owners must also comply with applicable benchmarking and grading disclosure requirements. NYC requires annual benchmarking by May 1 and the display of the assigned energy-rating label near each public entrance within 30 days after October 1.
Official requirements: NYC DOB — Local Law 33 Energy Grading.
For a buyer, the distinction matters during due diligence. A low score may call for an energy-performance investigation, while an F grade calls first for clarification of the missing submission and the building's compliance status.
Neither label alone establishes the cost of bringing a property into compliance with every other NYC building requirement.
How Building Owners Can Turn a Low Grade Into a Business Case
The objective should not be to improve a letter grade simply for appearance. It should be to improve the building's underlying performance in ways that support its operating economics and market position.
Start by reviewing the ENERGY STAR score, benchmarking records, monthly energy use, and any changes in occupancy or building operations. Confirm that floor area, property type, and meter data are accurate. Incorrect inputs can distort the score and lead to unnecessary spending.
Next, investigate the building systems. Potential opportunities include HVAC scheduling, controls optimization, retro-commissioning, lighting improvements, insulation, and targeted equipment upgrades. The right measures depend on the property's condition and energy profile.
Then assess the financial case. Estimate installation cost, annual energy savings, maintenance implications, financing, and applicable incentives. Consider whether the upgrade is likely to improve reliability or tenant comfort in addition to reducing consumption.
Finally, measure the result. Track energy use after the work and ensure benchmarking records reflect the building's actual performance.
A verified improvement can strengthen the owner's investment case. A grade change unsupported by meaningful operational results is a much weaker basis for claiming a financial return.
How to Evaluate the Effect on Rent and Sale Price
Owners considering an energy retrofit should avoid applying a research premium directly to their asking price.
A better approach is to assess three separate questions.
First, what savings can the project produce through lower energy consumption? This can be estimated from actual utility records and engineering analysis.
Second, could better performance reduce operating risk or improve tenant appeal? This requires a market assessment that considers similar properties, tenant preferences, lease structures, and the building's competitive position.
Third, would investors pay more for the improved property? An appraiser or real estate adviser can examine comparable transactions and consider the effect of operating expenses, capital expenditure, income, and perceived risk.
These benefits may overlap, so they should not simply be added together. For instance, a buyer's valuation may already reflect lower operating costs in its projected net operating income.
The most defensible investment case uses verified energy savings and property-specific market evidence, with broader research serving as context rather than as a guaranteed return.
Conclusion
Energy grades can influence property values and rents, but the effect depends on the market, building type, lease arrangement, regulatory environment, and quality of the underlying asset.
Research provides evidence of rental premiums for ENERGY STAR-certified U.S. office buildings, rental discounts for inefficient offices in the Netherlands, and a strong transaction-price response to a Dutch minimum energy-performance policy. Broader IEA research also finds that efficient buildings can command higher sale prices.
These findings support taking energy performance seriously as part of property investment and leasing strategy. However, they do not establish a fixed premium for NYC's Local Law 33 A–F grades.
For NYC building owners, the practical approach is to treat the grade as a market signal, verify the underlying benchmarking data, identify cost-effective improvements, and assess the financial benefit using actual consumption and local market evidence.
A better energy grade can strengthen a property's investment story, but durable value comes from demonstrated performance, manageable operating costs, and a building that remains attractive to tenants and buyers.